
Quantum Behavioural
Regime Intelligence
built for scrutiny
A (j, q) coordinate per asset on the SUq(2) quantum group, with bootstrap confidence intervals and an explicit applicability flag. Vector, not scalar. Honest scope, not alpha hype.
Apply for the Pilot ProgramBuilt for institutional buyers, not retail hype
Six structural buyer personas. One math. Each gets a tier that maps cleanly to their decision cycle and budget.
Six analytical capabilities
Each capability is verifiable from the open code and the forthcoming SSRN / arXiv preprint.
(j, q) Cluster Classification
Each asset receives a coordinate on the SUₚ(2) quantum group with bootstrap CI and a three-cluster classification: Equity-Index, Commodity, or Single-State.
Applicability Flag
Automatic flag when the framework does not apply — sparse-news assets, empirically single-state tickers, or pre-2014 windows where the bimodal regime has not yet emerged. Stated upfront, every measurement.
τ_dec Microstructure
Research observable for dealer-inventory cycles, τᵇ ≈ 106s on the analysed SPY tick dataset. Bouchaud-anchored (β ≈ 0.4), computed from tick autocorrelation and disclosed with the research methodology. It is not a live trading signal.
Bootstrap CI Attribution
Every (j, q) coordinate ships with a 95% bootstrap CI, bimodal detection rate, n-articles, and per-window breakdown. No single-shot estimate is ever shipped as truth.
Research News Ingestion
Polygon and GDELT batch inputs with documented provenance. Used as model inputs for controlled research, never claimed as an alpha signal.
Open Science
SSRN / arXiv preprint covering the SUₚ(2) framework, 16/16 unit tests, and source code plus test suite available for institutional due diligence under NDA. Method published, results reproducible.
Inside the console
Four views, four jobs to be done — plain English everywhere, technical detail behind expanders for the curious.
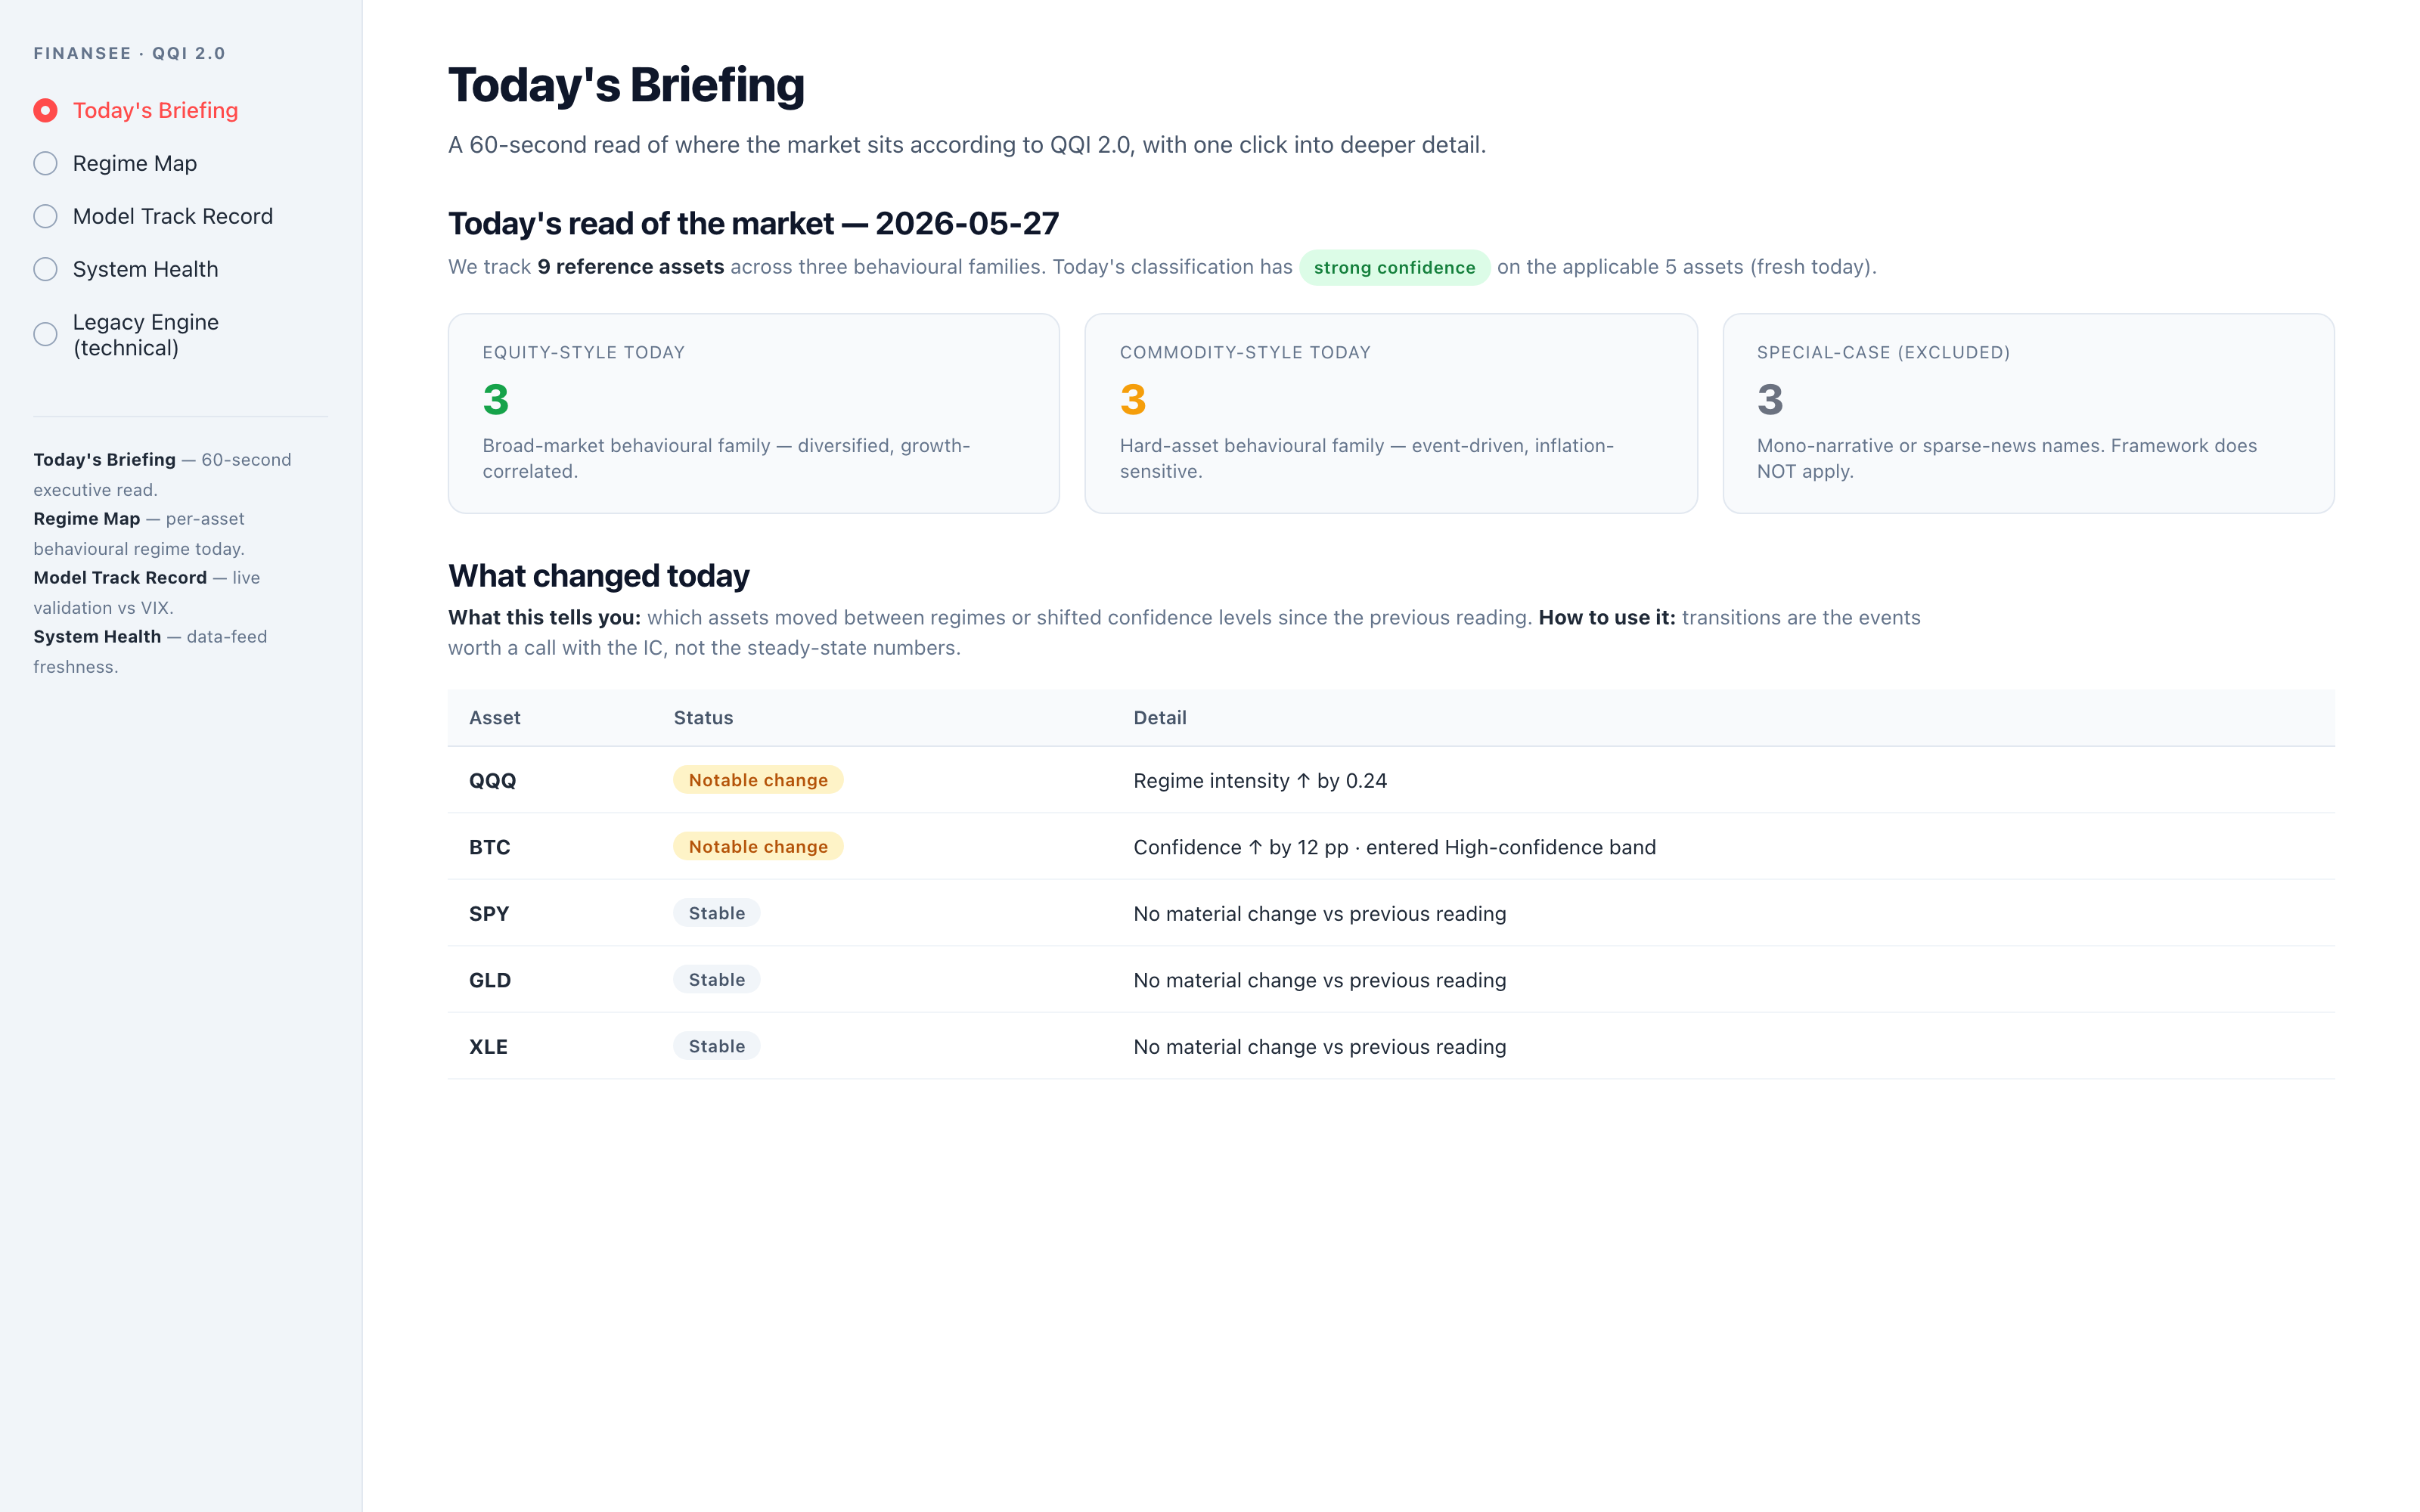
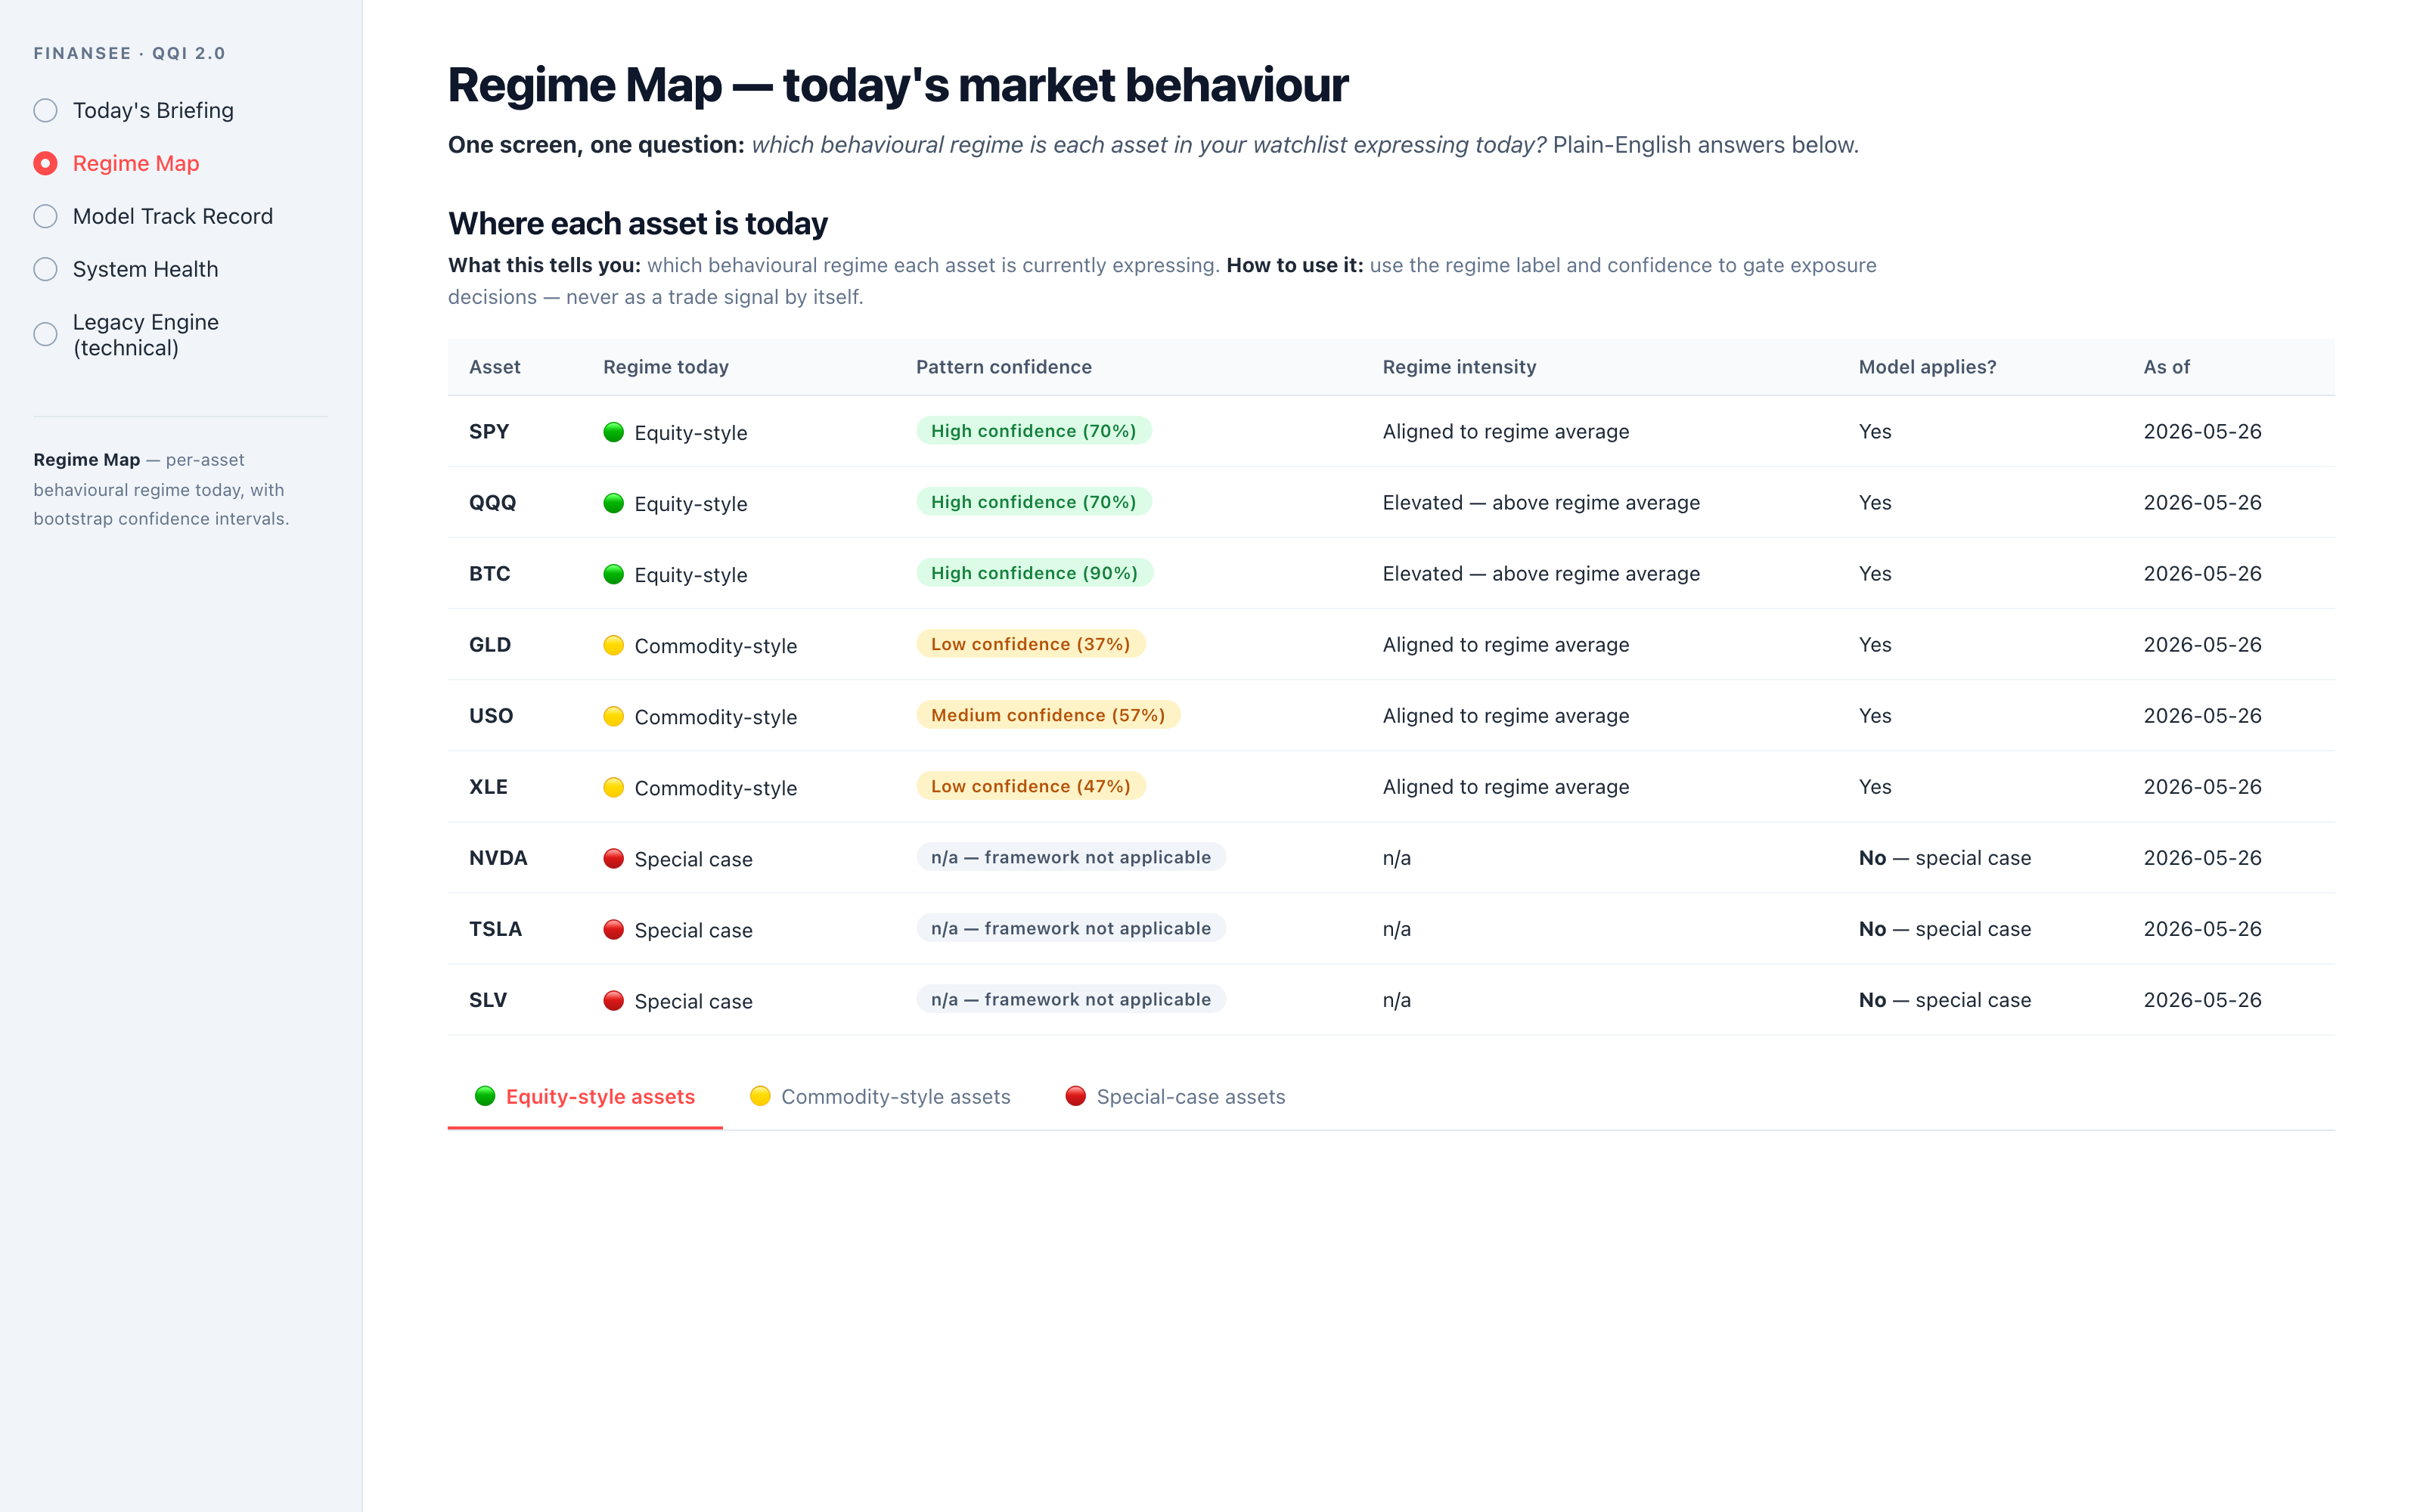
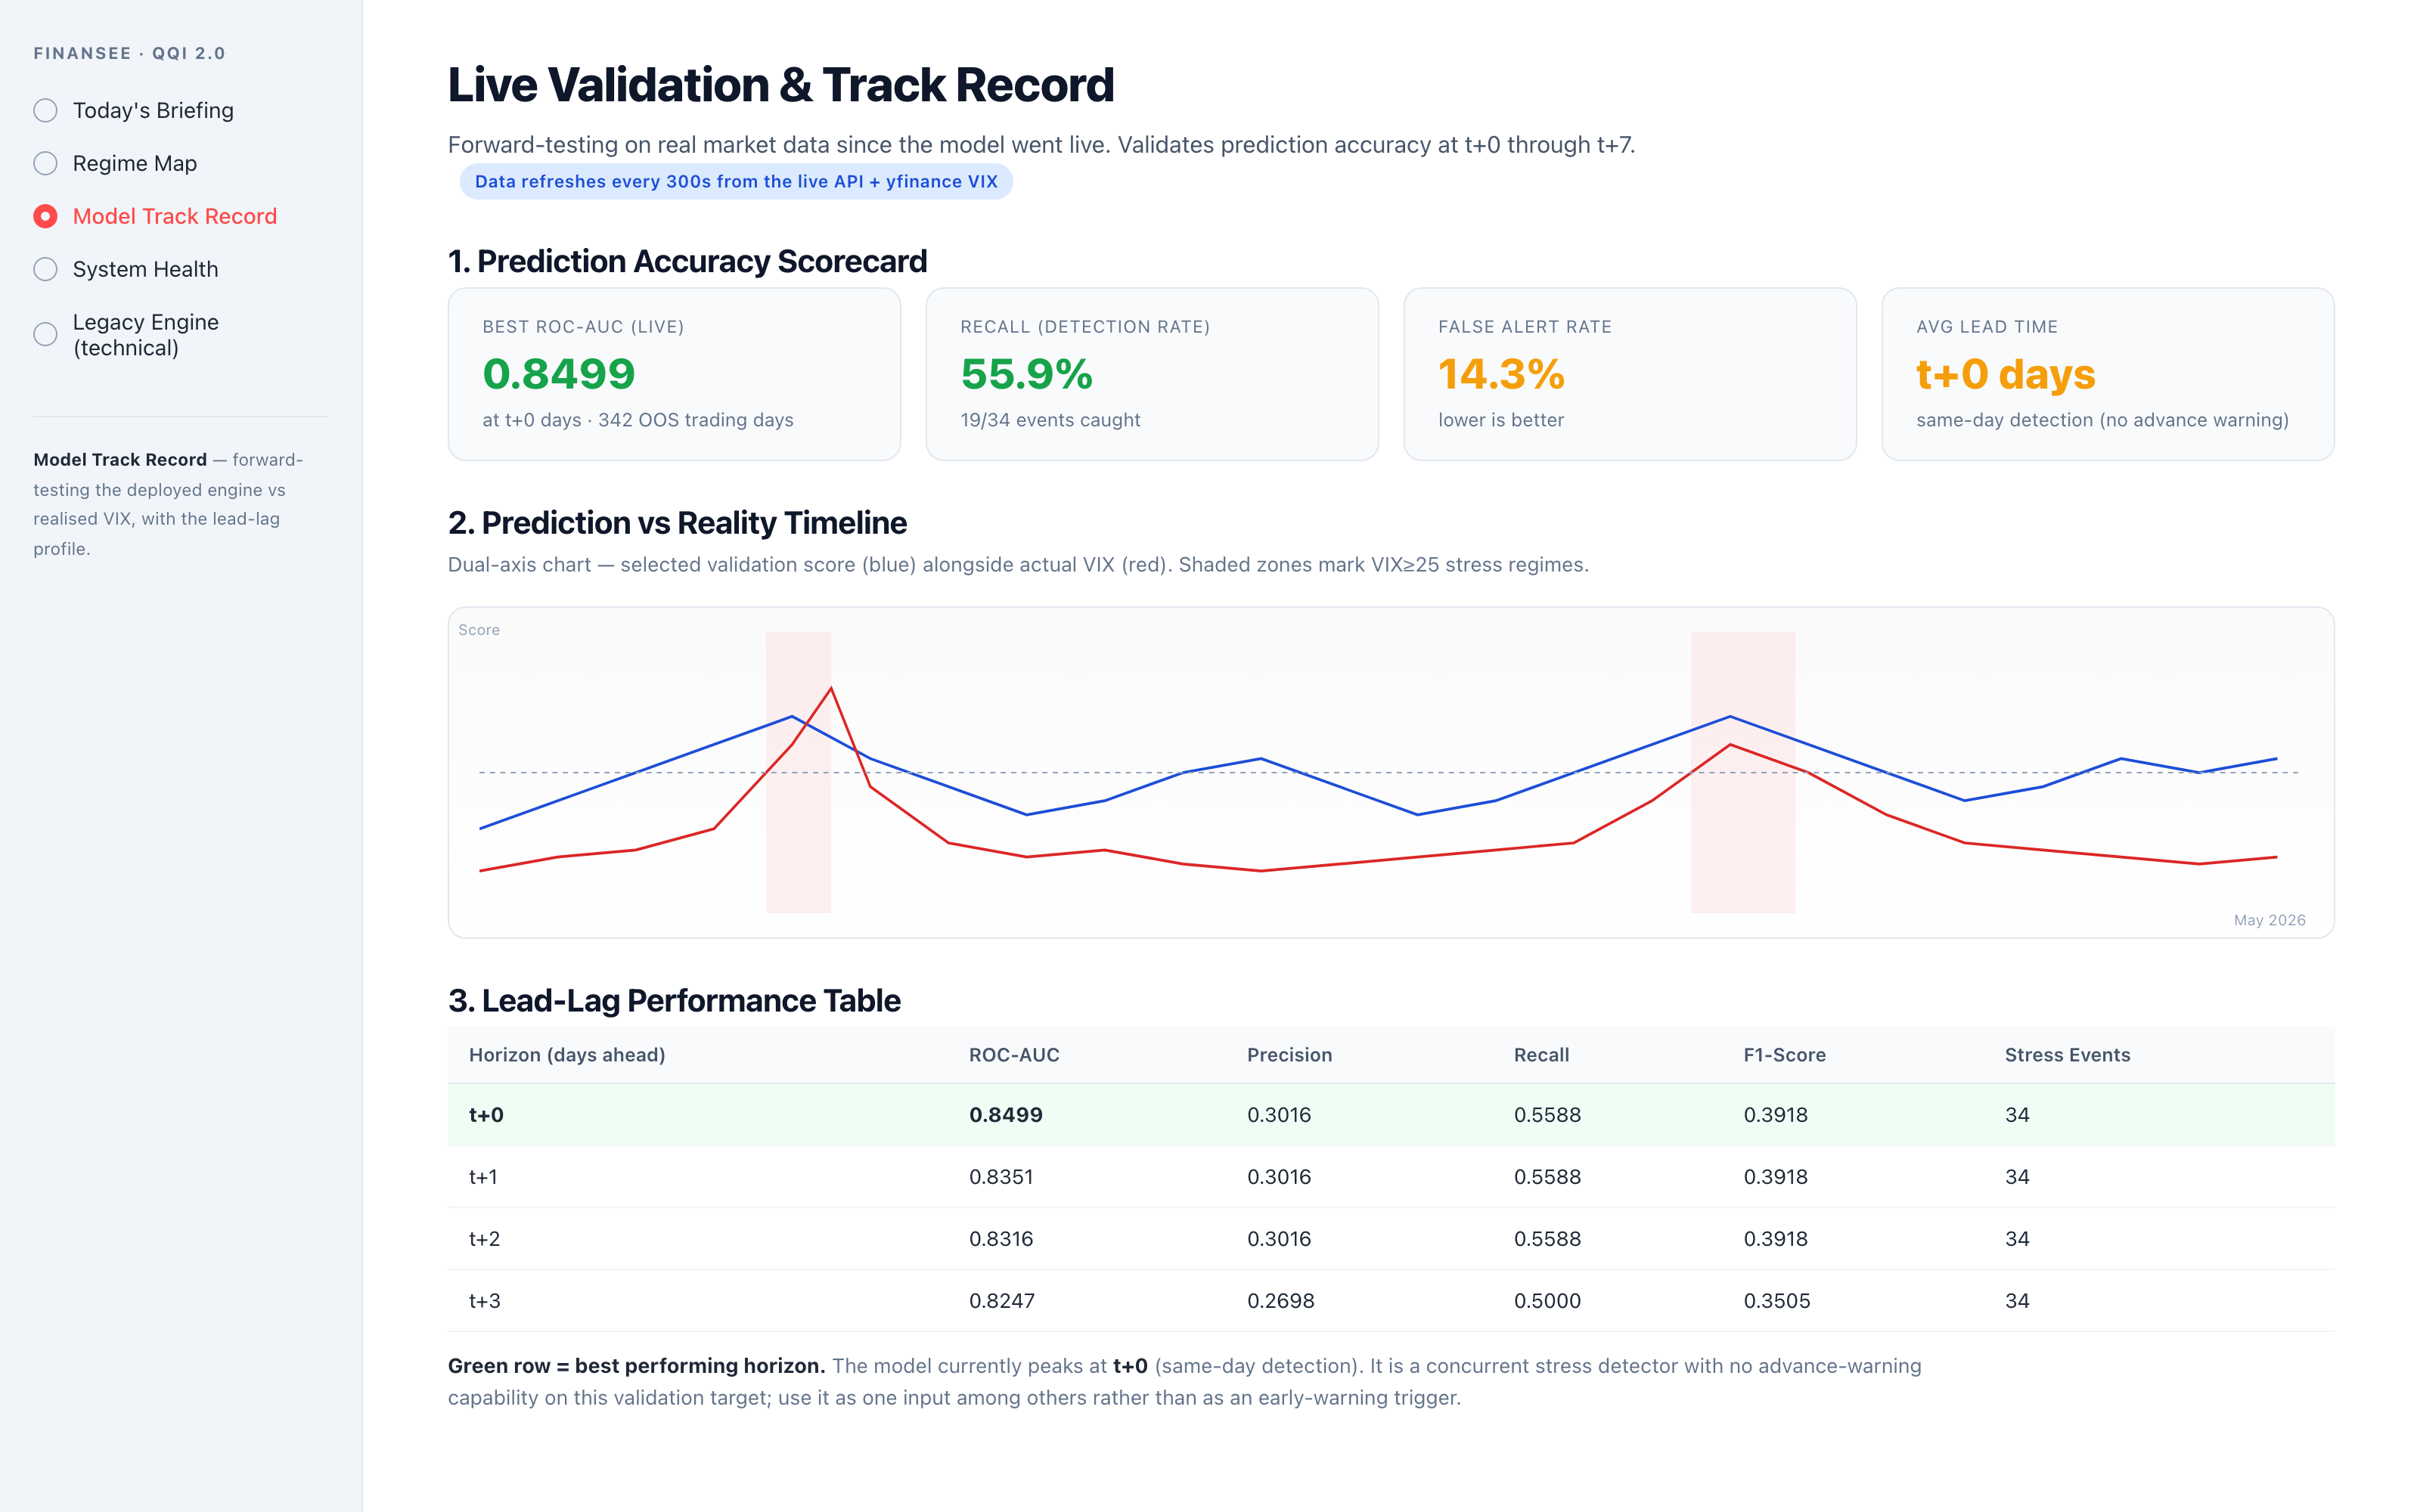
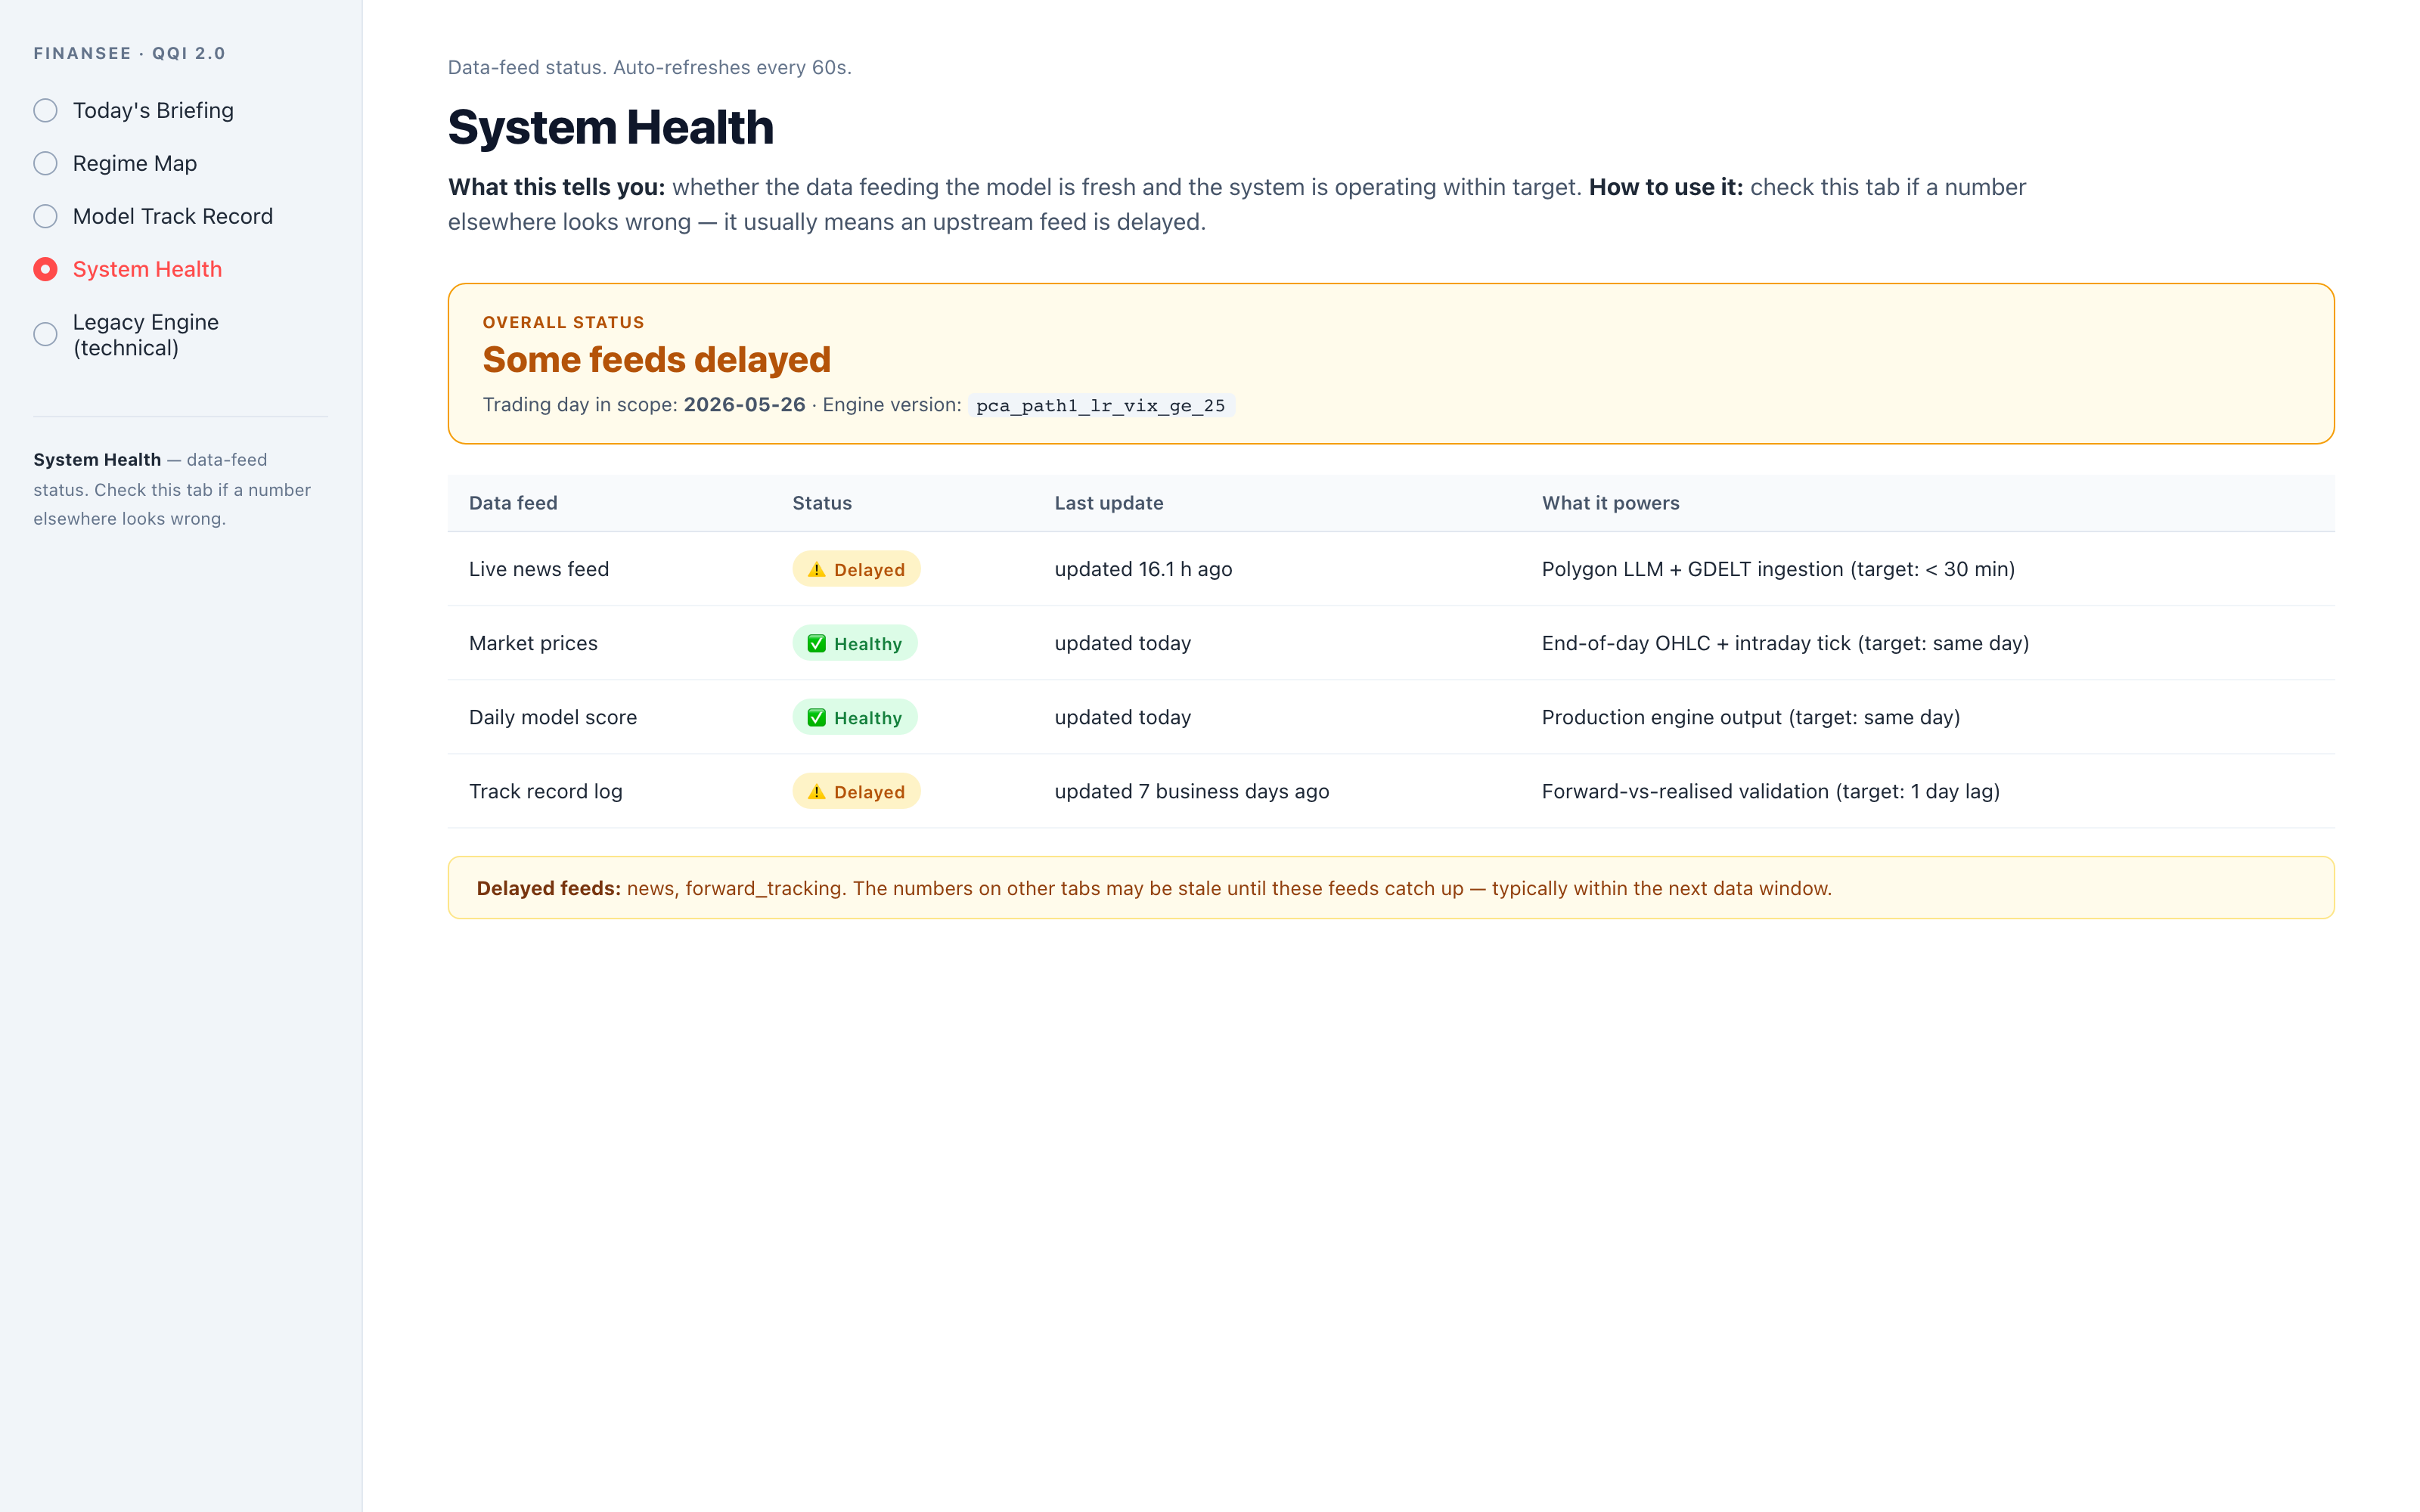
Pipeline
Ingest
Market data, multi-asset news feeds, and tick-level microstructure are batch-ingested for controlled research runs.
Encode
q-deformed 6j-symbol projection on SUₚ(2) quantum group recoupling theory.
Classify
Bootstrap CI on every (j, q) coordinate; applicability flag per asset; cluster transition detection.
Disclose
Per-run (j, q) research digest, cluster-transition review, and microstructure observable. No trade signal.
90-Day Pilot Program
We are onboarding the first 10 institutional partners (family offices, hedge funds, structured-product desks) for a 90-day evaluation. Commercial pricing is intentionally not published yet — the pilot is the only way in at this stage, and pilot partners help shape what the commercial framework will look like.
What's Included
- Full access to the live (j, q) console for pilot scope
- REST API access for approved pilot universe
- Daily (j, q) digest email (17:00 ET)
- Bootstrap CI on every measurement
- Cluster-transition alerts via Slack / email
- 30-minute onboarding call · weekly feedback calls
- Downloadable CSV reports
- 90 calendar days · paid POC pricing (institutional) or free Adviser trial (advisory)
Commercial pricing is intentionally not published yet. Pilot partners receive a detailed scope-of-work and the post-pilot commercial framework during onboarding.
Request Pilot Access
QQI is a descriptive indicator of the financial spin network's current (j, q) state, NOT a return predictor. Our research falsified return prediction on 9 of 11 task variants tested; we say so openly. The bimodal regime the framework describes emerges around 2014; on pre-2014 windows the framework is structurally inapplicable and the applicability flag says so. Every measurement ships with a bootstrap confidence interval. Not investment advice.